
Your home loan: your best rate and monthly payment
The short answer
You asked for the best rate and the lowest monthly payment you can get, given you would pay Lenders Mortgage Insurance (LMI) again if you moved. Here is what I found.
Your monthly payment at four home values
A bank valuation decides your rate and your LMI, so here's each one, as a new 30-year loan.
Where the rates* come from: my lender comparison tool, on 5 November. They're the lowest variable rates shown at those LVRs, leaving out loans limited to certain jobs or purposes.
How long a move takes to pay for itself
This matters if you might sell or move before long. It's when you would owe less than at NAB, paying the same dollars, and counting LMI, cash and about $350 in fees.
Try your own numbers
The yellow boxes are yours to change. Everything on this page updates as you type. These figures are the ones you told me when we spoke last, so please correct anything I have wrong.
How LMI works in your case
It doesn't move with you
NAB says its LMI can't be moved across to another lender when you refinance.
Part may come back
New LMI goes on the loan
You wouldn't pay it in cash, but you would pay interest on it for years.
The 90% line
No LMI at 80%
For engineers
The LMI waivers I know of are for others, such as medical and legal jobs.
A free extra: paying fortnightly
This won't lower your monthly payment, but it could take about off your loan, at NAB or anywhere else.
12 becomes 13
There are 26 fortnights in a year. Half a repayment, 26 times, makes 13 monthly repayments, not 12.
One extra repayment a year
Interest is worked out daily
Your bank works out interest on each day's balance. A lower balance sooner means less interest, every day.
Ask NAB to set it at exactly half your monthly repayment. A lower fortnightly figure would lose the extra repayment.
Your property report
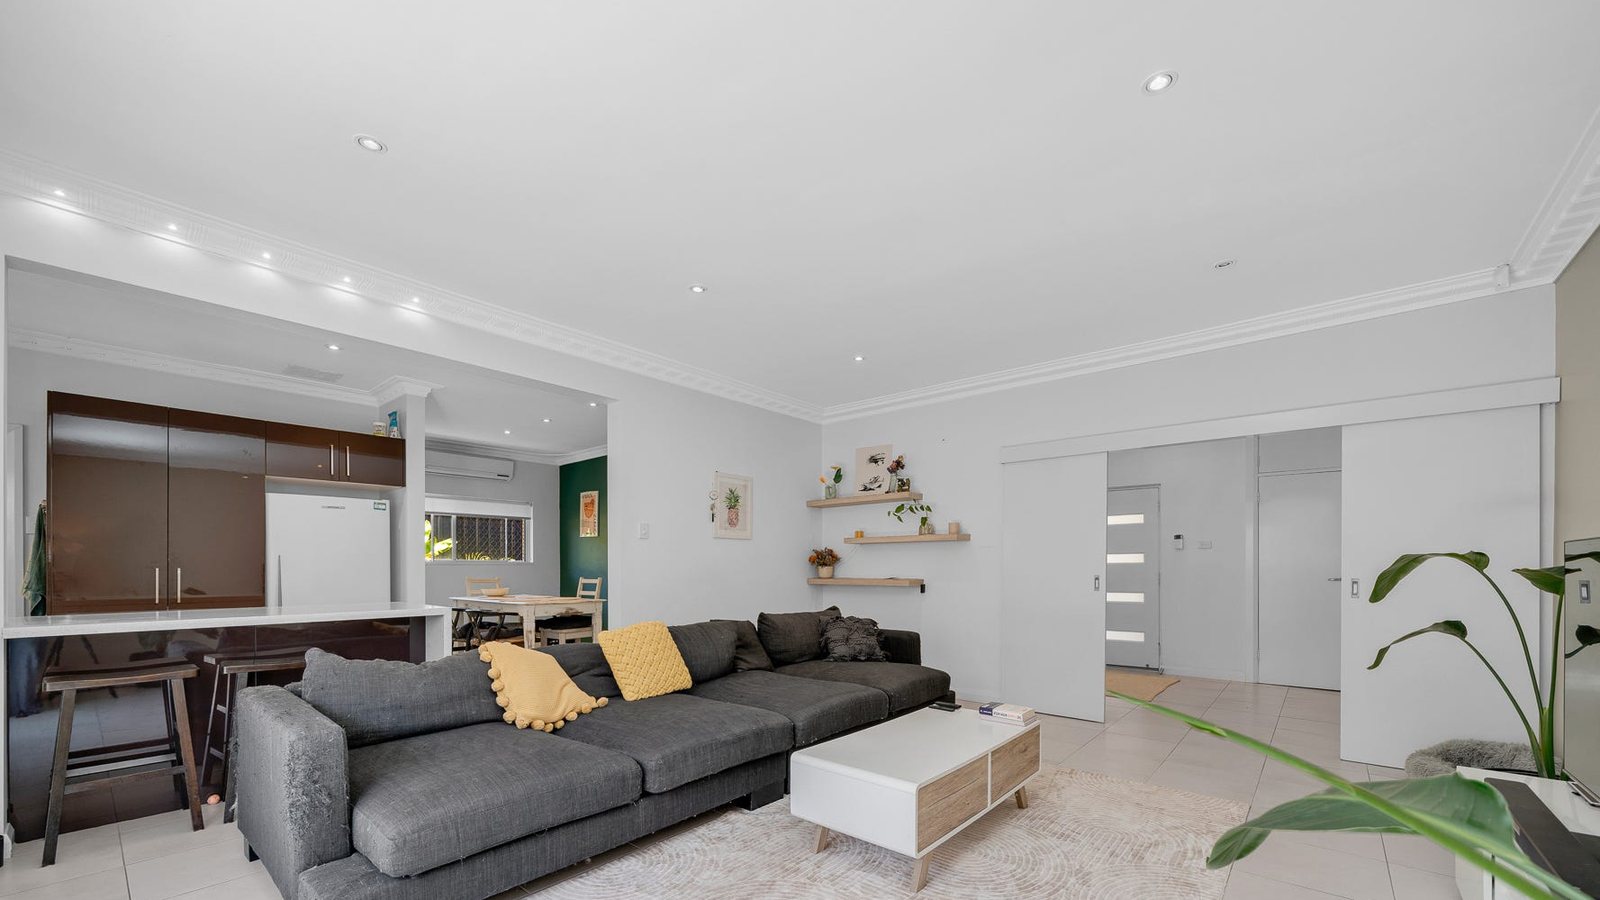
This is the report I showed you. It's a computer estimate, so a bank valuation could land differently, and that valuation decides how much LMI applies.
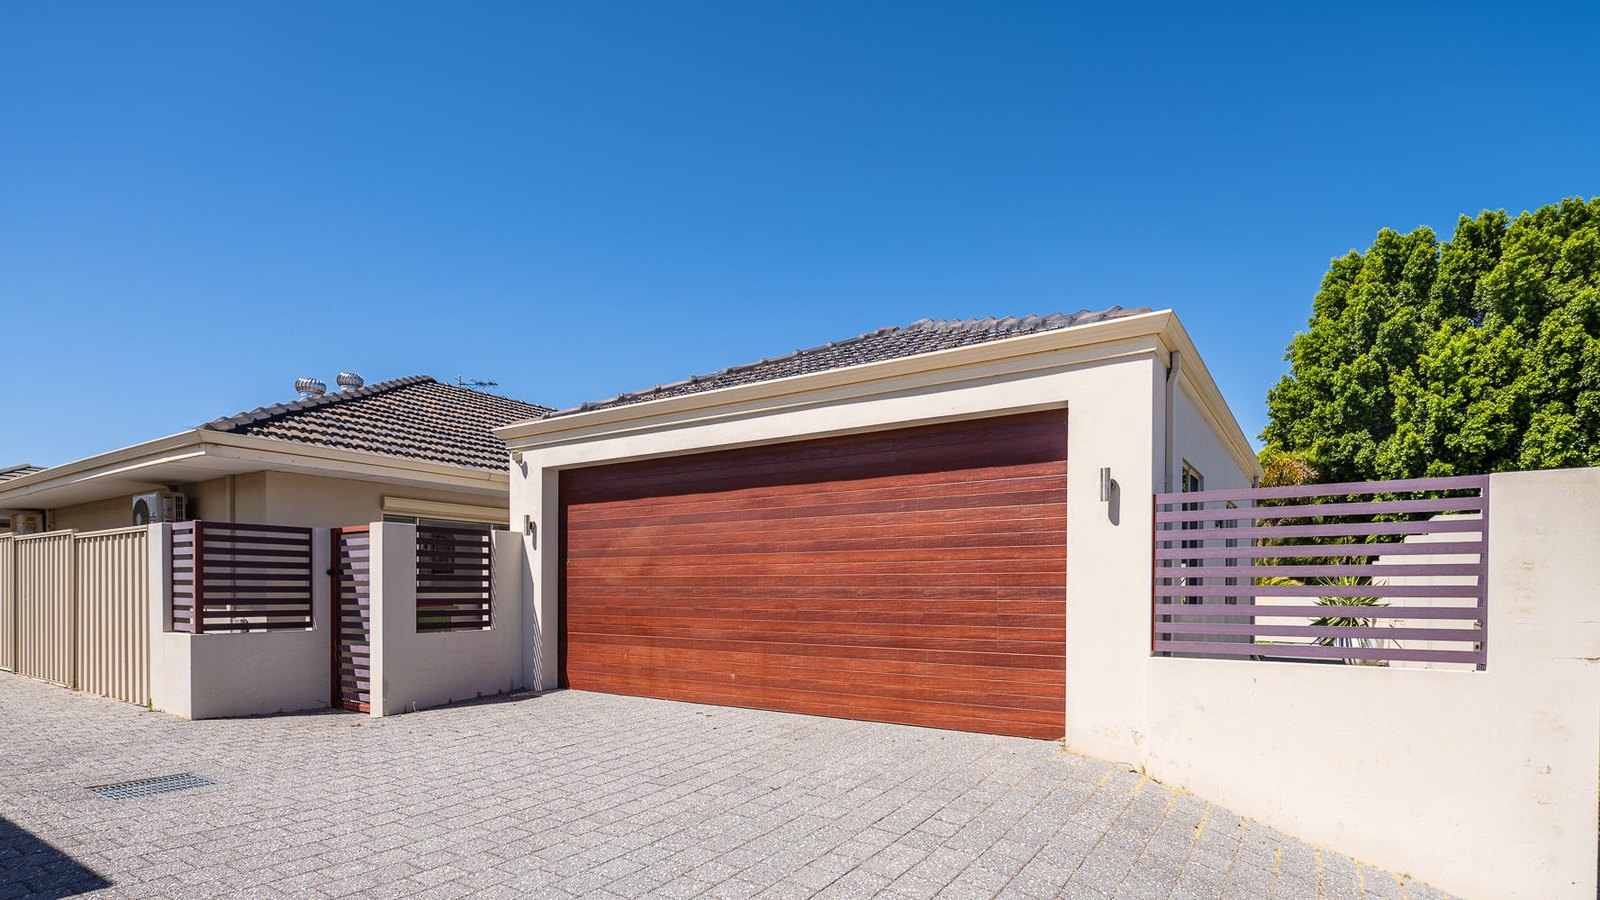
Photos on this page are from the Ross Realty listing of your home.
Worth a read
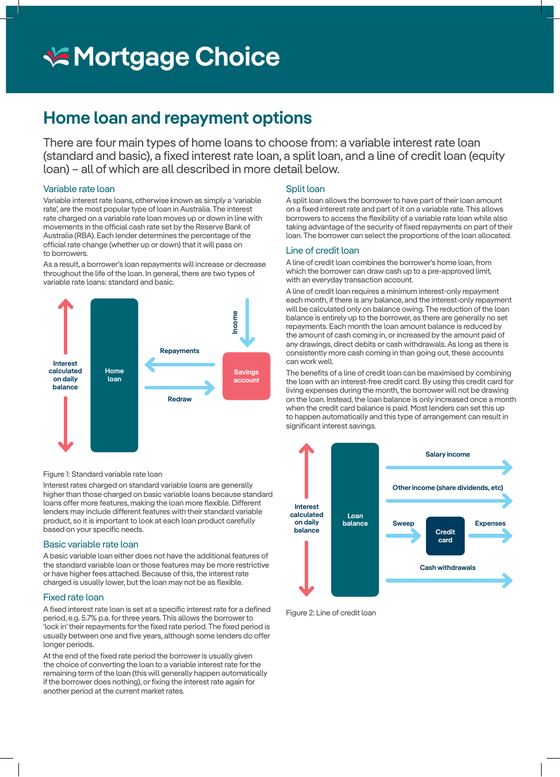
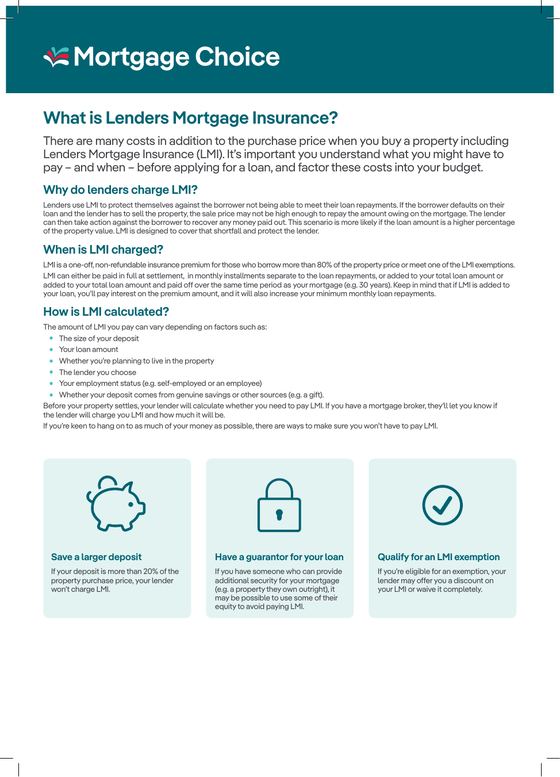
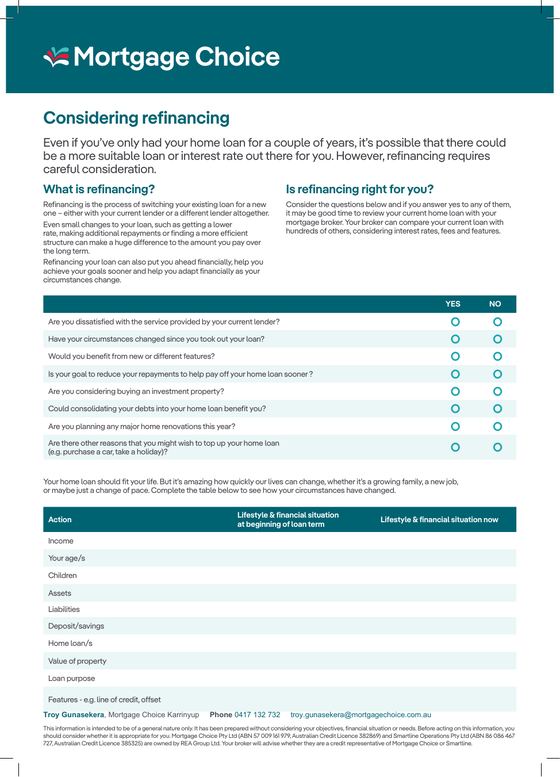
Three short Mortgage Choice fact sheets, picked for where you are up to.
What would help me next
Negin's eMail address
Thanks for yours, Amir. Negin needs her own consent link.
Your recent payslips
The two most recent from each of you, for the basics.
Your driver's licences
Both of them, so I can get your credit files with your consent.
Your latest NAB statement
It confirms your balance, your rate and any redraw.
Your LMI paperwork
The LMI amount, settlement date and insurer's name.
Your work and your plans
Your years as an engineer, and how long you'll keep this loan.
This page gives general information only and is not a loan offer, an approval or personal financial advice. The figures are estimates from what you told me, a computer property estimate and rates from before the Reserve Bank's rise on 3 November 2026. They hold each rate for the whole loan and leave out most fees, and rates will move. The LMI figures are my estimates until a lender quotes them. NAB's LMI page sets out its refund rules, and NAB would need to confirm how they apply to you.
Keyboard shortcuts
Press ? or Esc to close